Frontier Spirit: How scared should
the Big 4 be?
Mar/Apr 2022

The proposed merger between Frontier and Spirit Airlines promises, or threatens, to create a new ULCC force, the fifth biggest airline in the US market. Here we take a look at the merger from a macro perspective while, in the following article, Skailark presents a unique analysis of the combined cost and market competitiveness on a route-by-route basis of the two airlines.
The merger agreement was announced in February, is currently being reviewed by the US DoT and DoJ, and is expected to be finalised by the end of this year. Under the agreement Spirit Airlines will be acquired by Frontier Group Holdings for $6.6bn, of which $2.9bn is Spirit’s equity value and $3.7bn is the assumption of net debt and operating lease liabilities, with Frontier shareholders owning 51.5% of the new entity and Spirit shareholders 48.5%.
In term of traffic and revenues, Spirit is actually larger than Frontier — 2021 passengers totalled 30.8m and 20.7m respectively and revenues were $3.2bn against $2.1bn. Both companies have been recovering since the middle of last year but combined traffic in 2021 was still 10% down on 2019 while combined revenue was down 17% over the same period. The 2021 net results were both negative in 2021 — $473m at Spirit representing a margin on revenues of -14.6% and $102m at Frontier, equivalent to -5.0%.
In the depths of the pandemic (2020) the two airlines burnt through $(784)m in Operating Cashflow though this turned positive to the tune of $415m in 2021. Spirit in particular maintained heavy Capex through the pandemic with the result that combined Free Cashflow totalled $(1.3)bn during 2020 and 2021. However, the two airlines were able to raise $0.9bn in debt and $1.0bn in equity during these two years.
This has left both ULCCs with fairly solid balance sheets, with combined shareholders’ equity of $2.6bn and combined long-term debt of $7.5bn as at the end of 2021. Liquidity was good — $2.4bn in cash and equivalents for the two companies.
Both carriers received substantial government support through the Payroll Support Program (PSP) which covered expenditure for furloughed employees but their participation in government loan schemes under the CARES Act was minimal; as at the end of December Frontier had just $66m in CARES loans outstanding.
Indigo-incubated ULCCs
Bill Franke, the Chair of Frontier’s Board of Directors and the managing partner of Indigo Partners, which owns, through a fund, 82% of the airline, will be appointed Chairman of the Board of the combined company. It will be his responsibility to lead a committee that will establish the combined company’s management team, location of the headquarters and the new branding (Frontier Spirit would seem to be the obvious choice).
Spirit and Frontier have an intertwined history linked to the ULCC specialist investment fund. Having set up Spirit in 2006 Indigo sold out in 2014 in order to acquire Frontier and transform it into a Ryanair-type airline. The CEO of Spirit, Ted Christie, was formerly CFO at Frontier and Spirit’s COO, John Bandoraitis, held the same position at Frontier. Barry Biffle, CEO of Frontier spent eight years at Spirit, while his CFO, James Dempsey, came from Ryanair.
Both airlines strongly adhere to the key elements of the pure ULCC model — yield-driven demand, price leadership, high proportion of ancillary revenue (60% of total revenues), flexible asset location, modern same-family fleets, high productivity, rigorous cost control, clear decision-making processes, concentration on VFR and Leisure segments, etc. But they also have some unique US features — using loyalty programmes as part of the marketing strategy and selling connecting tickets.
As the map indicates, the two networks are mostly complementary, but with significant overlaps. Frontier is stronger in the west, particularly at Denver, its main base where 30% of its flights are operated; it also has a concentration in the Florida/Eastern seaboard markets. As well as Denver, Frontier has ten other bases, or “focus cities”. Spirit too has a strong Florida presence linking into the Midwest. Its main base is at Atlanta, and it has eight other operating bases. Spirit has a substantial Central/South American operation and a Mexican base at Cancun linking to Florida, but neither carrier flies to Mexico City, which is where Volaris, and its alliance with Frontier, fits in (see Aviation Strategy, February 2022).
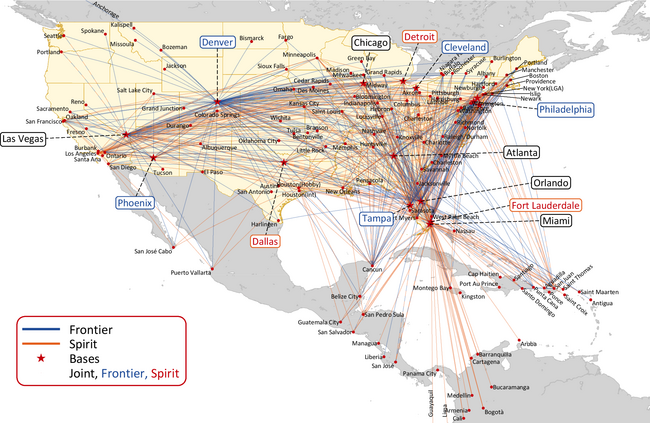
The merger will result in five Frontier Spirit joint bases — at Miami, Orlando, Atlanta, Chicago and Las Vegas. Whether this is enough to raise concerns about the joint airlines’ enhanced pricing power at the regulatory authorities is not yet clear. Having allowed through, even encouraged, the series of mergers that resulted in the Big Four, it is difficult to see how the Frontier Spirit merger could be refused, but nothing is certain.
The merged Frontier Spirit will compete in all sizes of markets but with a bias towards the large segment (500+ daily passengers) — 61% of the combined airline’s capacity against a national average of 46%. In the mid segment (200-499 daily passengers) it will deploy about 22% of capacity, roughly the same as the 23% national average; and the small segment (10-199 daily passengers) will account for 17% against 31% nationally. (By contrast, the other ULCC, Allegiant, concentrates predominately on small markets: 88% of its operations.) There are, according to the merger presentation, 2,000 market opportunities in the US waiting for Frontier Spirit to exploit.
As a leisure carrier (96% of traffic is estimated by management to be leisure or VFR), Frontier Spirit does not have to rely on frequency but the merger should improve its attractiveness just through providing more options to travellers. For example, on Baltimore-Orlando, the Big Four currently have nine daily departures but post-merger Frontier Spirit will be able to offer five (two from Frontier, three from Spirit).
There are also the international links to the other Indigo ULCCs. Volaris, the leading Mexican carrier, has an extensive codeshare agreement with Frontier. Longer-term there has been speculation about Wizz eventually deploying its A321XLRs on the Atlantic; however, the immediate future might involve cross-leasing spare capacity as Wizz’s expansion plans are being thwarted by the war in Ukraine. (There are no obvious connections to JetSMART the Chilean ULCC in which American Airlines has just taken a minority stake.)
Costs versus the Legacies
Frontier Spirit’s ULCC model provides it with a unit cost advantage that the network carriers cannot begin to match because of the complexity of operating hub and spoke systems, having multi-type fleets and, feeding intercontinental services plus having legacy employment and IT issues. But Frontier Spirit also makes Southwest, the great LCC innovator, almost look like a Legacy in cost terms.
In the merger presentation, Frontier Spirit’s combined adjusted CASM was contrasted with the rest of the US industry (see chart). These unit costs were normalised to a 1,000 mile sector, and net interest was added to operating costs). The three network carriers were over 70% more expensive than Frontier Spirit; Southwest was 34% more expensive.
Frontier Spirit’s pricing is based on what it describes as “an ultra-low base fare of only $54” with ancillaries doubling the revenue per passenger to around $108 (see chart). Again comparing with the three network carriers, their revenue per passenger would be around 80% higher than Frontier Spirit’s; Southwest would be about 20% higher.
Fleet plan and market implications
As at the end of 2021 Frontier had 234 aircraft on order, all A320/21 neos while Spirit had an orderbook of 156 neos, which will be split among A319s, A320s and A321s, with delivery schedules out to 2027 and 2028 respectively. The Frontier orderbook mostly results from Indigo’s mega-order in 2017 for 430 A320 Family aircraft to be allocated among Frontier, Wizz Air, JetSMART and Volaris. The combined Frontier Spirit fleet plan envisages a growth in total aircraft from 283 units at the end of 2021 to 493 by the end of 2026, a CAGR of 12% pa. The proportion of neos in the fleet is set to increase from 43% to 79% over the same period.
What does this imply for Frontier Spirit’s position in the US market? Using pre-pandemic utilisations and factoring in probable seat capacity growth, the combined airline would be on target to carry close to 120m passengers in 2026 compared to the pre-pandemic peak of 58m. Impressive growth, but Southwest in 2019 carried 163m passengers and Ryanair’s pre-pandemic medium term forecast was for 200m-plus passengers. It doesn’t yet tie in with Barry Biffle’s prediction that “ULCCs will dominate US airspace”.
A comparison of the structure of the US domestic market and the intra-European market is interesting. In 2019, the last normal year, Frontier and Spirit had gained about 8% of the US market; the ULCC total, adding in Allegiant, was around 10%. In Europe the two main ULCCs — Ryanair and Wizz — had some 20% of the market, twice the US proportion.
Moreover, post-pandemic the ULCCs will inevitably gain market share as the result of relative scale of the fleet expansion plans. In an even more price-conscious era this could pose a threat to the LCCs — Barry Biffle has suggested that Southwest might have to “migrate up”. Southwest and JetBlue account for 29% of the US market while easyJet and other smaller carriers have only about 17% of the European market.
The three major network carriers have about 54% of the domestic US market while the three European carriers have about 39% of their internal market, shares which are likely to be eroded in the upcoming years though any significant incursion into the main hubs on either side of the Atlantic still looks very difficult and probably not worth the risk.
One of the issues the Frontier Spirit has to address if it is to achieve a European-scale market penetration is passenger approval. The graph, which comes from DoT surveys, and was definitely not included in the Frontier Spirit merger presentation pack, reveals that in 2021 the two airlines received by some margin the most complaints per passengers carried of all the US airlines. Spirit’s record was worse than Frontier’s but both ULCCs fared badly on most measures — refunds (a particular problem during the pandemic), delays timeliness, reliability, misplaced luggage.
Ryanair of course receives a fair amount of abuse from its customers, but on key service metrics like dispatch reliability and on-time performance it can claim to be at the top of European rankings. So the service aspect does have to be improved at Frontier Spirit. However, on other ESG criteria, Frontier can boast of being the US’s greenest airline while Spirit picks up awards for employment conditions and diversity.
Synergies etc
Coming out of the recession, Frontier Spirit confidently asserts that it will win because it has the lowest costs. It points to the experiences of Southwest post the Gulf war in 1991/92, Ryanair post 9/11 and Spirit after the Financial Crisis, which all boosted their margins and grew rapidly while the industry as a whole continued to suffer.
In claiming $500m of “run rate operating synergies” from the merger, management have been able, unusually for the industry, to give some concrete examples of improved efficiencies. Amalgamating the schedules will free up spare aircraft, ie aircraft needed to assure the schedule but which are not fully utilised — the equivalent of five aircraft in total. Another six aircraft will be freed by removing inefficiencies in the joint schedule mix and improving aircraft utilisation. Savings are estimated at $145m (or $12m per aircraft which seems reasonable). Another $35m is expected to come from additional traffic through new connecting possibilities.
There is also the opportunity afforded by the merger to match capacity more closely to demand. Interestingly, management notes that its airlines underperform on load factor compared to global ULCC benchmarks. In 2019 Frontier’s load factor was 86% and Spirit’s 84%, significantly below Ryanair’s 96% (though calculated on seats sold rather than actual passengers). Pushing up the joint load factor by 2-4 points would generate $220m of revenue synergies.
The remaining $100m comes from procurement savings and overhead efficiencies (a suspiciously round number). Nothing, the company admits, is included for dis-synergies.
IT integration is frequently a big headache when merging two companies. Frontier and Spirit both use the standard Navitaire reservation system, which is important, but their yield management systems may not be compatible. Both airlines are unionised — over 80% of employees — and are in the middle of five-year contracts with ALPA and other bodies. These contracts will probably have to be renegotiated, leading to the perennial issue of integrating seniority lines. Then there is the ultimate merger question — whose name goes on the door of the CEO’s office?
“Win-win” is an expression beloved of management consultants and investment bankers, which often proves to be a delusion. Nevertheless, Frontier Spirit puts forwards a convincing risk analysis of revenue and cost risks to the merged airline compared to the Big 4. This is summarised as:
-
If both leisure and business traffic fail to recover to pre-pandemic trends, the Big 4 will have to cut excess capacity and/or raise fares, which means that Frontier Spirit relative fare advantage widens, plus the revenue synergies from the merger.
-
If leisure traffic recovers but business traffic doesn’t, the Big 4 will be forced to increase leisure fares to compensate for the loss of essential premium revenue, again increasing Frontier Spirit’s relative fare advantage.
-
If the crude oil price remains at over $100/bbl, Frontier Spirit’s cost advantage over the Big 4 increases because it uses 10 gallons to fly one seat 1,000 miles whereas the Big 4 need 15 gallons (an alternative view would be that ULCCs’ fuel costs are a higher proportion of the total cost pie than network carriers’).
-
Ex-fuel inflation is more manageable at Frontier Spirit than at the Big 4 because of the ULCC’s skill in cost control, plus the costs synergies resulting from the merger.
-
Finally, “Covid Debt” is much lower at Frontier Spirit relative to the whole US airline sector — $4 per passenger versus $21 per passenger.
Will JetBlue spoil the party?
At the beginning of April JetBlue made an unexpected $3.6bn bid for Spirit, valuing the airline at approximately $700m more than in the Frontier deal. The key question for Spirit shareholders is whether JetBlue’s extra cash upfront compensates for the increased implementation risks of the merger.
There would appear to be nowhere like the same degree of compatibility between operating models. JetBlue’s CASM (adjusted) would be 50% higher than Frontier Spirit’s. Its focus is on transcontinental operations and preparations for entry onto the North Atlantic. With its MINT premium product, it is orientated towards business travellers. Unit revenue per passenger is 70% higher than at Frontier Spirit. Moreover, JetBlue is entangled in an antitrust case with the DoJ over its alliance with American in the northeast of the US, which the DoJ contends is leading to market control and higher fares.
Whereas the Frontier Spirit message is pretty clear — “Creating America’s most competitive ultra-low fare airline”, the rationale for the takeover given by Jet Blue’s CEO, Robin Hayes seems slightly nebulous: “What we want to do is create a bigger JetBlue”.
| $m | 2019 | 2020 | 2021 | $m | End 2021 | |
|---|---|---|---|---|---|---|
| Revenues | 2,508 | 1,250 | 2,060 | Fleet assets (inc lease rights) | 2,872 | |
| Net result | 251 | (225) | (102) | Investments etc | 326 | |
| Operating Cashflow | 171 | (557) | 216 | Cash | 918 | |
| Capex | (62) | 12 | (63) | Other current assets | 119 | |
| Other Income (Expenditure) | (1) | (4) | Total Assets | 4,235 | ||
| Free Cashflow | 109 | (546) | 149 | |||
| Increase (decrease) in debt | 120 | 156 | 125 | Long term debt | 2,379 | |
| Equity raises (Dividends) | (159) | 266 | Other current liabilities | 1,326 | ||
| Total Cashflow | 70 | (390) | 540 | Total Liabilities | 3,705 | |
| Shareholders' Equity | 530 |
| $m | 2019 | 2020 | 2021 | $m | End 2021 | |
|---|---|---|---|---|---|---|
| Revenues | 3,831 | 1,810 | 3,231 | Fleet assets (inc lease rights) | 6,292 | |
| Net result | 335 | (429) | (473) | Investments etc | 405 | |
| Operating Cashflow | 551 | (225) | 209 | Cash | 1,535 | |
| Capex | (455) | (553) | (351) | Other current assets | 308 | |
| Other Income (Expenditure) | (2) | (1) | (1) | Total Assets | 8,540 | |
| Free Cashflow | 94 | (779) | (144) | |||
| Increase (decrease) in debt | (120) | 1,295 | (664) | Long term debt | 5,150 | |
| Equity raises | 367 | 376 | Other current liabilities | 1,276 | ||
| Total Cashflow | (26) | 882 | (432) | Total Liabilities | 6,426 | |
| Shareholders' Equity | 2,114 |
| In fleet (End 2021) | On Order | ||||||
|---|---|---|---|---|---|---|---|
| Frontier | Spirit | Total | Frontier | Spirit | Total | ||
| A319 ceo | 31 | 31 | |||||
| A320 ceo | 16 | 64 | 80 | ||||
| A321 ceo | 30 | 30 | |||||
| Sub-total | 16 | 125 | 141 | ||||
| A319 neo | |||||||
| A320 neo | 73 | 48 | 121 | 76 | |||
| A321 neo | 21 | 21 | 158 | ||||
| Sub-total | 94 | 48 | 142 | 234 | 156 | 390 | |
| TOTAL | 110 | 173 | 283 | 234 | 156 | 390 | |
