WestJet: Hidden within Onex
Jan/Feb 2026


WestJet, one of David Neeleman’s airlines, was seen in the 2000s as the dynamic newcomer challenging staid Air Canada. It is based at Calgary, the largest city in Alberta where the economy is driven the hydrocarbons industry and whose citizens, uniquely among Canada’s provinces, do show some support for the 51st State concept.
WestJet went through a transition from a pure LCC to a hybrid, expanding internationally with 787s and 737MAXs, and setting up a ULCC subsidiary (Swoop, which was reintegrated into the mainline carrier in 2023). The transition process eroded WestJet’s profitability, and the unit cost gap between WestJet and Air Canada almost disappeared.
In 2019 Onex, a Canadian private investment fund, made a successful bid for WestJet, offering C$3.5bn (US$2.6bn) cash, roughly 67% above the C$2.1bn that the Toronto stockmarket had been valuing the airline at that time. The Onex deal was driven by Gerry Schwartz, the former CEO of the $59bn AUM fund, who back in 1999 had launched a bid for Air Canada, with the intention of merging the flag-carrier with Canadian, but that bid was blocked at the last minute.
WestJet’s management fully welcomed the take-over, but the deal went through just before the pandemic struck. Since then, WestJet has been buried within Onex. It has issued zero financial information on the airline since the takeover. Apart from occasional on-time performance stats, it has issued no revenue, capacity or traffic results, and had made only the broadest press statements. For 2025 it was reported in the Canadian press that it carried 22.6m passengers, which would be a decline of about 10% from the 2019 peak of 25m. (For comparison, Air Canada’s 2025 total of 45.5m was 12% down on the pre-pandemic 2019 figure of 51.5m.)
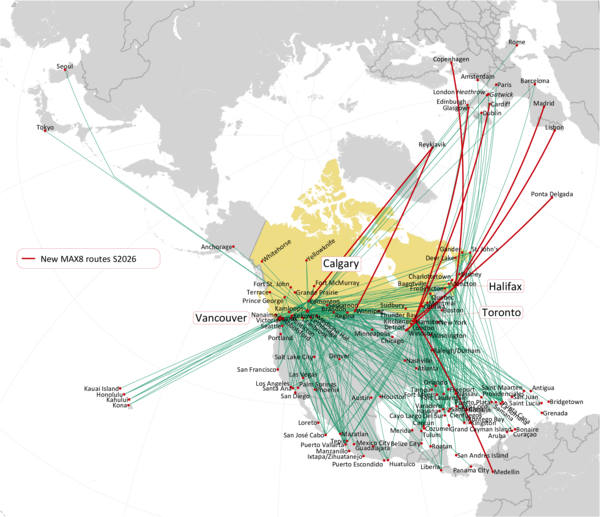
Immediate plans look similar to Air Canada Rouge, retreating from the US transborder market and concentrating 737MAX-8s on thinner routes in Europe: new 2026 services include Toronto-Cardiff, and Halifax to Madrid, Lisbon, and Copenhagen. New South American points include Medellin in Columbia and São Paulo in Brazil. It also has to integrate the 18 737s it acquired from its takeover of the charter carrier Sunwing in 2025.
Private equity companies make their profits from exiting — selling or refloating purchased companies, having turned their operations around, usually through cost cutting. Onex’s overall target return on investment is 20% pa over a 5-8 year period, but that timescale will have been disrupted by the pandemic. That RoI would imply target price for WestJet of at least C$10bn, or about twice Air Canada’s current stockmarket value.
CEO of WestJet is Alexis von Hoensbroech, appointed in 2022 and previously CEO of Austrian Airlines. The board also contains a number of ex-CEOs with formidable Network, LCC and Hybrid experience: Alex Cruz (Vueling and BA), Ben Smith (Air France, Air Canada and Rouge), Christoph Mueller (Aer Lingus) and Bob Fornaro (Spirit).
WestJet’s ordering activity is consistent with its ambitions. Last September WestJet announced the purchase of 60 737-10 MAX aircraft, with options for an additional 25, plus seven 787-9s with options for four more. This brought the total firm orderbook to 123 aircraft, compared to Air Canada’s 68.
| In service | Avg Age | Orders | |
|---|---|---|---|
| 737-700 | 36 | 19.5 | |
| 737-800 | 58 | 13.0 | |
| 737MAX | 57 | 5.0 | 116 |
| 787-9 | 7 | 5.9 | 7 |
| 158 | 11.3 | 123 |
However, to achieve its goals Onex, acting like all private equity companies, must load WestJet with debt and sell assets. This leverages the return on equity, if the company improves its financial performance (the opposite effect if the financial situation deteriorates).
Onex is obliged to share private WestJet financials with the credit rating agencies in order to obtain a rating for its bonds. Last June Fitch rated WestJet’s long-term debt as just “B” (same as JetBlue) and revised its outlook to negative.
Fitch commented, just before the extent of the transborder traffic decline became apparent, that it expected WestJet’s margins to come under pressure and remarked specifically about its financial structure:
“Gross adjusted leverage may rise towards 7x in 2025 from 5.9x at YE 2024. EBITDAR fixed charge coverage is projected to remain weak for the rating, potentially falling near 1x this year. WestJet has heavily engaged in sale-leasebacks in recent years, allowing it to raise significant liquidity through the pandemic years and beyond, but drove up lease-related charges. Lease liabilities have risen to C$3.5bn as at March 2025 from C$2.2bn in 2022 … failure to restore fixed charge coverage to around 1.5x could trigger a negative rating action...
“WestJet’s 'B’ rating is three notches below its primary domestic competitor, Air Canada (BB/Stable). This difference reflects WestJet’s higher near-term leverage prospects, more limited financial flexibility, and smaller relative size”.
However, Fitch and the other agencies have not taken into account the role WestJet may play within the SkyTeam global alliance. In May 2025 Delta acquired a 12.7% equity stake in WestJet from the Onex Group, with Air France-KLM taking up a further 2.3% and Korean Air buying 10%, leaving Onex with 75%.
The full significance of this ownership structure is unclear but Alexis von Hoensbroech sounded optimistic: “A milestone in our airline partnerships, building on existing relationships and reflecting confidence in WestJet’s strategy, performance, and people.”