Avianca
A tale of intrigue
Oct/Nov 2021

Avianca Holdings, South America’s second largest airline group, immediately after celebrating its 100th year of continuous operation was one of the first to file for Chapter 11 protection in the US courts in the wake of the pandemic and forced closure of operations in May 2020.
It is also one of the first to have its restructuring plan approved by the court and seems set to emerge from Chapter 11 before the end of the year. The business plan it put forward suggests that it will be operating a dramatically different airline business model, and one that is portrayed as potentially profitable.
The events of the last few years leading up to the Covid-19 crisis were dramatic for Avianca and its shareholders. The story could provide the basis of a plot for such as a John Grisham novel featuring corporate intrigue and power play. Ideal for a long-haul flight from Bogotá.
The protagonists
- Germán Efromovich, a self-made billionaire — according to the Financial Times his first job was selling encyclopaedias door-to-door and later started and sold a quail farm; while working as a tutor at an adult school he taught a union leader named Luiz Inácio Lula da Silva, who later became president of Brazil (2003-2010). The Bolivian born son of Polish refugees had built, with his brother José, a Brazilian conglomerate — Synergy Group, registered in Panama — based on oil exploration but with fingers in other pies including telecommunications and shipbuilding. The brothers apparently got into running airlines when a client repaid debts to the oil company with an aircraft in 1998. That grew into Oceanair which started scheduled Brazilian operations in 2002. In 2004 he buys Columbia’s Avianca out of Chapter 11 for an initial $64m. Oceanair later rebranded as Avianca Brasil (though never owned by Avianca).
- Patrician Roberto Kriete, born into El Salvador’s elite, a billionaire and one of El Salvador’s richest men. His father Ricardo Kriete had bought a controlling stake in the national airline TACA in 1961, and Roberto ran the airline successfully for many years even during the vicious civil war.
- United Airlines, one of the three major US network carriers, eager to build a strategic presence in South and Central America, fight off Delta planning the same, both attacking American Airlines' preeminent position on the continent.
The plot
Avianca and Grupo TACA merge in 2010 to create a market-leading group of 11 airlines operating in nine countries in Central America and the Andean region of South America. The new holding company AviancaTACA (later renamed Avianca Holdings) was incorporated in Panama.
The relationship between the two billionaires initially appears amicable. Efromovich’s Synergy Group ends up with two thirds of the enlarged group (held through Panama-registered subsidiary Synergy Aerospace) while Kriete’s Kingsland Holdings (registered in the Bahamas) holds 33%.
A shareholders' agreement is signed to ensure Kriete’s rights as a minority shareholder (including board representation, veto on specific board proposals, tag-along rights and buyout terms), and Roberto Kriete serves as the group’s Chairman from 2010 to 2013.
The group lists non-voting preferred shares on the Bogotá exchange in 2011 (Synergy and Kingsland retain all the voting rights through their holdings on Ordinary shares). The group returns to the New York Stock Exchange in 2013 in an IPO of ADSs representing preferred shares valuing the combine with a market capitalisation of $2bn: during the process Kingsland sells a higher proportion of its holding ending up with 14% of the equity and 22% of the voting rights.
Over the subsequent years Avianca grows at a strong pace — increasing capacity at around 6-10% a year — and successfully consolidates the separate airlines under the single Avianca brand.
But revenues come under pressure (growing at an annual average of just 1% in the five years to 2018) from the incursion of LCC rivals into its home markets; and profitability is diminished (operating margins averaging 6% and net margins 1.4%). Roberto Kriete, it is reported, successfully vetoes the incorporation of Synergy’s heavily loss-making Oceanair (operating as Avianca Brasil) and Avianca Argentina into the holding company.
Through this period Avianca significantly increases the size of its fleet, ending 2018 with nearly 196 aircraft up from 150 five years earlier. It seems that it had plans to continue to grow, with orders for 124 A320neos for delivery between 2019 and 2025 along with orders and options for 12 787s. It also builds up a high level of debt: it ended 2018 with long-term debt and capital leases of $3.4bn and total liabilities of $6.1bn. Total assets were $7.1bn and book equity $978m. Its adjusted net debt/EBITDAR ratio stands at 6.2x. Cash reserves amount to only $389m (8% of annual revenue). By the end of 2018 its stock market capitalisation falls to $550m, a quarter of its IPO valuation. The board sees a financing crunch: over $2bn of its total debt would mature within three years.
To understand the stresses on Avianca, we go back a few years to find that Synergy itself is stressed. In 2015 EISA, a Brazilian shipbuilding subsidiary of Synergy Group, goes bust with secured debts of $295m owed to Elliott Management, a New York based hedge fund run by Paul Singer and one described by the Financial Times as ruthless. It appears that Synergy and Elliott have had a long-standing relationship over many years. It appears also that Synergy Group has pledged the majority of its shares in Avianca to Elliott Management as collateral.
In the same year, to raise much needed cash, Avianca sells 30% of its frequent flier programme, LifeMiles, to a private equity firm Advent International for $340m.
In 2016 trouble brews at Avianca Brasil as Wells Fargo tries to sue for non-payment of leases.
In early 2017 Roberto Kriete’s Kingsland Holdings files a lawsuit against Avianca Holdings, Germán and José Efromovitch, and United Airlines. The aim is to block a proposed strategic partnership between Avianca and United. Kingsland alleges that Efromovich secretly negotiated Avianca’s proposed partnership with United for his own benefit (essentially as a bailout of Synergy) at the expense of Avianca and minority shareholders.
According to the complaint, the deal included a $800m loan from United to Synergy, backed by Avianca and Oceanair shares. Half of this would be used to repay existing Synergy debt (including defaulted loans from Elliott) and $130m would go to Oceanair, while Avianca itself would only receive about $200m.
Kingsland also claims Avianca’s liquidity problems had been caused by Efromovich’s “misconduct”, accuses Efromovich of channelling Avianca funds to his private companies through non arm’s length related-party transactions, and alleges that Synergy used “Avianca’s assets to shore up Efromovich’s other financially-strapped business concerns”. Kingsland claims that Avianca board meetings resembled a “corporate politburo rubber-stamping Efromovich’s initiatives without advance notice, deliberation, independent judgement or hesitation”.
Kingsland also claims that Synergy’s pledge of Avianca shares to back its loans violated the Kingsland-Avianca shareholders’ agreement, as Synergy did not request Kingsland’s approval, and third-party creditors were not permitted transferees of Avianca shares.
Maybe what really riles Kriete is that representatives from Elliott turned up at board meetings as special advisors, and may have been instrumental in negotiating with United without including him.
Avianca Holdings then files a retaliatory lawsuit against Kingsland and Roberto Kriete to stop Kingsland’s “improper actions” aimed at blocking the pending alliance with United and “any further dissemination of the company’s confidential information”. Its defence of the United deal notes that while Delta and Copa were also interested in Avianca, their proposals required a change in control, which Synergy would not accept. It accuses Kingsland of trying to “take over the company” with other partners, and argues (somewhat bizarrely) that Kriete’s Mexican airline Volaris (founded 2005) competes with Avianca in Central America.
United again
Both sides stop calling each other names and withdraw their lawsuits. Negotiations restart with United, with Kriete this time on board. Avianca Brasil, possibly also supported by Elliott Management, struggles on but eventually goes to the wall at the end of 2018, thus removing it from the equation.
The deal with United is finally signed, setting up a tripartite joint venture (subject to regulatory approval) between United, Avianca and Copa. United’s President, Scott Kirby, is quoted as saying that the agreement “represents the next chapter in US-Latin American air travel,” adding that United, Copa, and Avianca will provide “a better overall experience for business and leisure customers travelling across the Western Hemisphere”.
United provides a loan to Synergy of $456m, to allow it to pay off its defaulted loans to Elliott Management. Synergy transfers its entire Avianca shareholding to a new subsidiary, Delaware-incorporated BRW Aviation LLC, to act as collateral. The terms of the five-year loan are subject to several covenants benchmarked against Avianca Holdings' financial performance. United, in a separate agreement with Kingsland effectively also assumes the obligations of the Shareholders' Agreement between Synergy and Kingsland to satisfy Kriete’s concerns as a minority shareholder.
Have the Efromoviches got away with it? But no! In April 2019, Synergy breaches at least one of the terms of the United loan: Avianca Holdings fails to comply with a collateral coverage ratio set down in the agreement. United takes control of the Avianca shareholding, handing the voting power to Kingsland to ensure ownership and control covenants attached to debt and leases, ousts Germán and José Efromovich along with other Synergy appointees from the Board, and installs Roberto Kriete as Chairman.
“This is an important day. It is the right time to build a promising future for the company,” Kriete tells Colombian El Tiempo.“Turning around the company will be a difficult challenge. My role is not to be the hero of this drama. My role is to assemble a world-class team who have the skills to lead the transformation of Avianca.”
Avianca 2021
Before Synergy’s default, Avianca had already announced a restructuring transformation plan, named Avianca 2021, to change its focus from growth to profitability.
With a new management team in place, Kriete sets about intensifying the implementation: culling the fleet by 25%, renegotiating aircraft commitments, divesting non-core business units, and strengthening the capital structure.
The team negotiated successfully with debt providers to re-profile over $5bn in debt (without needing to involve the courts), improved the cash position through asset sales and sale and leasebacks, and even raised $375m of new liquidity.
Financially 2019 was a very poor year: underlying operating profits of only $44m (from $4.6bn revenues) don’t quite cover $300m in interest costs. Restructuring charges of $600m incorporating asset write downs, redundancy payments and professional fees, pushes the group into an annual reported loss of nearly $900m, and virtually wipes out the net equity position on the balance sheet.
But, by February 2020, Avianca is tracking ahead of profitability and liquidity goals, giving hope that it would reach its 2021 targets. Roberto is back in control. Germán and José Efromovich will shortly be charged with bribery and money laundering.
A happy ending.
New business plan
That sensational plot line did not exactly prepare Avianca for the Covid-19 pandemic.
Already having gone through a financial restructuring under its own steam, there was not much room for Avianca to cope with the enforced closure of operations. The entire fleet was grounded in March 2020 and borders did not start to reopen until September. (The total numbers of passengers carried fell to 7.9m for the whole of 2020 down from 30.5m the year before.) It had no other choice than to file for Chapter 11 protection.
It had some government support through the process — Columbia provided $370m of the $1.4bn debtor-in-possession (DIP) funding approved by the courts in late 2020. At the same time Kingsland and United maintained support through a second tranche of DIP funding convertible into equity on emergence from Chapter 11.
This was all refinanced (with the approval of the courts) in July 2021 with facilities of $1.6bn, providing it with an extra $200m in liquidity and sufficient for the courts to then approve the group’s business plan to allow it to exit Chapter 11 protection before the end of the year.
The most important of its airlines subsidiaries have survived, but the group allowed the Peru operation to fail in 2020 and has now closed its domestic operations in the country.
For the new business plan Avianca engaged management consultants Oliver Wyman to conduct a deep review of the strategic alternatives. The review suggested a further shift in the company’s strategic direction to focus on an efficient cost structure and a network optimised for point-to-point leisure and VFR traffic — accepting that business travel and connecting international travel will take a very long time to recover.
The rationale behind the plan seems to be that the LCC business model has shown the value of flexibility and high ratios of variable- to fixed-costs: the company highlights that best-in-class LCCs have significantly outperformed legacy carriers through the crisis. It hopes that measures available under the Chapter 11 process will allow it to reduce its unit costs to, or even below, competitor LCC levels (see chart).
The new business plan appears to be a traditional boilerplate for restructuring. It envisages that Avianca Holdings will remain a portfolio of aviation businesses. But at its core will be what the company describes as a highly-efficient narrowbody operation following all the prime elements of a low cost business model (with some exceptions) — simplicity, point-to-point, unbundled fares, ancillaries. It believes that it will retain superior market positioning, and (somewhat questionably perhaps) provide a better product than LCC competitors to give it a revenue premium.
As part of this process it will be increasing seat density — it projects average seats per departure rising from 144 to 170 — and concentrate short haul flying entirely on the A320 family. It has renegotiated its outstanding order with Airbus, but the plan suggests that its short haul fleet will reach 133 units by 2026 up from 96 at the end of 2021.
| 2019 | 2025 | |
|---|---|---|
| Destinations | 79 | 85 |
| Routes | 145 | 245 |
| Daily departures | 662 | 698 |
| Routes per City | 1.8 | 2.9 |
| Departures per Route | 4.6 | 2.8 |
| Departures per City | 8.4 | 8.2 |
It will also significantly restructure its network offering. As shown in the table, by 2025 it is planning to increase the number of destinations offered modestly, the number of routes by 100 up from 145, increase the number of routes per city by a third and nearly halve the frequency of departures by route. This involves a higher proportion of non-hub point-to-point service. The average stage length is also expected to increase from 900km to 1,500km and aircraft utilisation to rise from 10 to 12 hours/day on the short haul fleet.
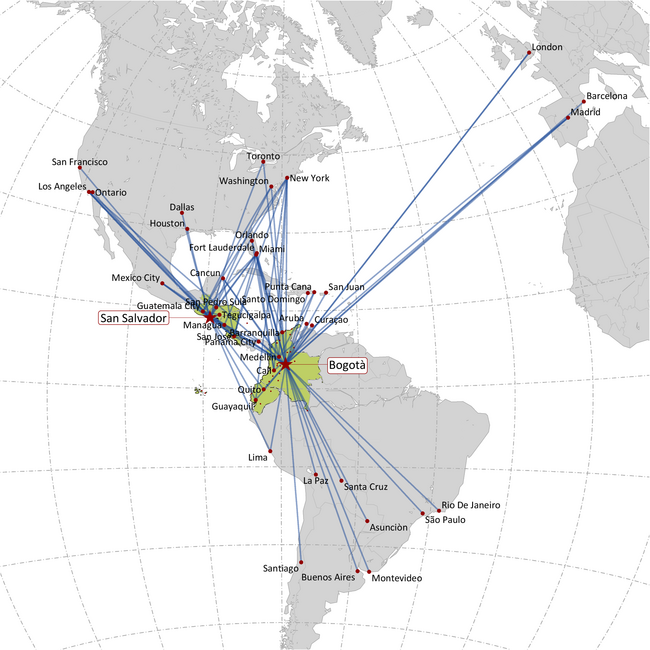
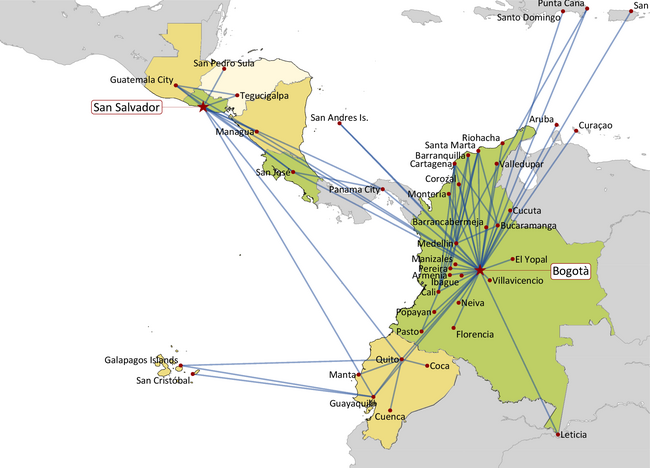
The long haul operations are planned to be streamlined to a single operating type, retaining the 787 and disposing of its remaining A330s (see fleet table). The plans suggest a stable twelve widebodies in the fleet (half the number it had at the end of 2019) for the next six years, and that it will operate a limited service to Europe and Los Angeles that can stand on its own. But it will also treat long haul as a non-core “supplemental business unit”, presumably based on point-to-point services into Bogotá and San Salvador, with what it calls “accidental connectivity”.
| 2019 | Δ | 2021 | ... | 2026 | 2027 | 2028 | ||
|---|---|---|---|---|---|---|---|---|
| Narrowbody | A319 | 27 | -5 | 22 | 10 | 10 | 10 | |
| A320ceo | 57 | 57 | 73 | 56 | 43 | |||
| A320neo | 10 | +2 | 12 | 50 | 73 | 92 | ||
| A321 | 13 | -8 | 5 | |||||
| A321neo | 2 | -2 | ||||||
| 109 | -13 | 96 | 133 | 139 | 145 | |||
| Widebody | A330 | 10 | -3 | 7 | ||||
| 787-8 | 13 | 13 | ||||||
| 787-9 | 1 | 1 | ||||||
| 24 | -3 | 21 | 12 | 12 | 12 | |||
| Regional | ATR72 | 15 | -2 | 13 | ||||
| E190 | 10 | -10 | ||||||
| 25 | -12 | 13 | ||||||
| Total passenger fleet | 158 | -28 | 130 | 145 | 151 | 157 | ||
| Freighter | A330F | 6 | 6 | |||||
| A300F | 5 | -2 | 3 | |||||
| 767F | 2 | 2 | ||||||
| Cargo Fleet | 13 | -2 | 11 | 11 | 11 | 11 | ||
| Group Fleet | 171 | -30 | 141 | 156 | 162 | 168 |
It will also retain cargo operations (one of the two cash generative businesses it held in the last two years) as a separate entity. with a dedicated fleet of 11 aircraft. It is using this as collateral for its exit loans with a business value of $870m and equity value after associated debt of $660m.
The third stand-alone business operation will be the frequent flier programme LifeMiles. During bankruptcy it spent a modest $5m to buy back in some of the stake it had sold in 2015 for $340m — it now owns 89.9% of the unit and has an option to acquire the remaining 10.1% for a similar amount. But this too has possibly been cash generative in the past two years. Perhaps Avianca has been influenced by United’s experience of raising funds from its monetisation of MileagePlus into thinking that an FFP really can be a separate business. It is using it as a source of collateral for the exit debt financing ascribing it a business value of $2.2bn and an equity value of $1.9bn. (For our views on FFPs see Aviation Strategy August 2020).
The Group has bravely set forth a business plan covering projections for the years up to 2028. It expects that it will have restored capacity to pre-pandemic levels by 2023 (see graph) but does not expect traffic volumes fully to recover until 2024.
In general, leisure and VFR traffic is projected to recover more quickly than business traffic, with faster recovery assumed in domestic and short-haul international flying. The Company expects leisure demand to reach 2019 levels by early 2024 (see graph), while business demand remains impaired versus 2019. It believes that the stronger and faster recovery in the leisure/VFR segment further supports the Company’s business model shift to focus on low-fare point-to-point flying.
It is anticipating significantly lower yields through the recovery, not expecting to reach 2019 levels of revenue until 2025. But it, perhaps rather aggressively, is suggesting that operating profits will exceed the previous peak ($294m in 2017) by 2023 with $423m, and that the restructured network will be able to generate operating margins averaging 15% in the following five years. This will result in an ability to target investment grade ratings over the period with gearing forecast to fall from a ratio of 5.1x net debt to EBITDA at the end of 2022 to below 1.5x by 2028.
When Avianca emerges from Chapter 11, it is clear that existing shareholders will receive nothing. It is likely that Kingsland and United — both DIP tranche ‘B’ lenders — will emerge with some proportion of equity, but it will be intriguing to see who else appears on the register of new shareholders.
In a rather interesting twist, the Group proposed to the courts that its reincarnation would be as a company based in London and incorporated in England and Wales. We can only assume that this was a pre-requisite of some of the funders: the UK has a legal system that recognises Chapter 11 restructuring. And the UK is not a tax-haven.
| US$bn | Jun 2021 | Dec 2019 |
|---|---|---|
| P&E | 4.61 | 4.95 |
| Goodwill/intangibles | 0.48 | 0.51 |
| Other fixed assets | 0.08 | 0.10 |
| Cash etc | 1.05 | 0.40 |
| Stock | 0.08 | 0.09 |
| Drs | 0.20 | 0.23 |
| Other | 0.20 | 0.99 |
| Current Assets | 1.53 | 1.71 |
| ST debt | (5.66) | (0.87) |
| Crs | (0.53) | (1.40) |
| Advance tickets | (0.42) | (0.34) |
| Other | (0.41) | (0.12) |
| Current Liabilities | (7.02) | (2.73) |
| Net Current Assets | (5.49) | (1.02) |
| LT Debt | (1.09) | (3.98) |
| Crs | (0.02) | (0.01) |
| Provisions etc | (0.48) | (0.54) |
| Net Assets | (1.90) | 0.01 |
| Represented by: | ||
| Share capital | 0.83 | 0.83 |
| Retained earnings | (2.68) | (0.54) |
| Reserves et al | (0.04) | (0.08) |
| Shareholders’ funds | (1.88) | 0.21 |
| MI | (0.02) | (0.20) |
| Net Equity | (1.90) | 0.01 |
| Ratios: | ||
| Net debt | 5.69 | 4.46 |
| Net debt/Equity | -300% | 86,286% |
| Net debt/EBITDA | -50.6x | 7.0x |