Volaris: Circumstances
Beyond its Control
Nov/Dec 2023

As the aviation industry emerged from pandemic in 2022 one of likely winners seemed to be Volaris, which had developed a very effective operating model, was in a strong competitive position, and was highly rated by the US equity analysts. Its fundamentals remain the same, but circumstances have conspired against the Mexican ULCC.
Volaris’s share price has consistently underperformed the North American average since 2021 — see graph — and at the end of 2023 the airline was valued in the equity markets at $1.04bn, which seems rather modest compared to Wizz which is valued at $3.0bn on the London stock exchange. Both ULCCs use the same basic operating model, having been incubated by Indigo Partners, and it could be argued that growth prospects for Volaris in Central and North America are better than those for Wizz in Eastern and Western Europe.
Volaris has been listed on the Mexican Stock Exchange and the NYSE since its IPO in 2013, with Indigo Partners, the founding entity, retaining a minority stake, around 16%. Enrique Beltranena has been CEO of Volaris since March 2006, and is highly respected throughout the industry. It is the only publicly quoted airline in Mexico. Its ULCC rival Viva Aerobus is privately owned by IAMSA, Mexico’s largest bus company, with the joint founder Irelandia, the ULCC investment fund, having sold its 49% stake in 2016. Plans for an IPO on the Mexican and New York exchanges have been mooted for at least 10 years, but CEO Juan Carlos Zuazua, does not seem particularly interested at this time.
Aeroméxico, Mexico’s semi-flag-carrier, is majority owned by Apollo Management, the New York-based private equity giant, following an extensive Chapter 11 bankruptcy reorganisation designed to rejuvenate the carrier as an efficient full-service operator. Its shares have been suspended since the end of 2022, but the CEO Andrés Conesa has indicated that a relisting could be implemented in 2024.
Financials
After a very strong performance in 2021 Volaris’s financials for 2022 were hit badly by a 68% increase in its unit fuel price at the same time as its yields came under pressure as capacity rapidly returned to the Mexican domestic and international markets. Its total revenues rose by 29% to US$2.85bn but operating costs rose 55% to $2.8bn, cutting operating profit to $44m from $397m. A net loss of $(80m) was reported compared to the previous year’s $106m profit.
For the first nine months of 2023 revenues were up 16% to $2.4bn, driven by 15% RPM growth and a 4% increase in total revenue per passenger, which in turn was the result of a 10% decline in average fares and a 24% increase in unit ancillary revenues. But operating costs rose by 13%, largely caused by the impact on labour costs from an unexpected appreciation of the Peso — from an average of Mex$20.7 to the Dollar in 2022 to Mex$17.6 in 2023. In 2022 Volaris switched from reporting its financials in Pesos to Dollars, which meant that its mostly Peso-based labour costs inflated by 38% when translated into Dollars, wiping out gains from falling kerosene prices. With an increase in depreciation/amortisation charges, the reported net result was a loss of $(104m) for January-September 2023, a margin of -4.1%. For the full year, Volaris guides to revenues of $3.2bn, a 13% increase on 2022, but with a downgrading in the projected EBTDAR margin, it looks likely that there will be another deterioration in the net result. The balance sheet shows long-term debt of $3.2bn against shareholders’ funds of only $131m, but most of the debt is in the form of capitalised leases. Liquidity at $764m looks fine.
The 2023 financials will be a disappointing contrast to the post-pandemic optimism of 2021 when Volaris was able to claim one of the highest net profit margins in the world. The airline has had to deal with two external events — the GTF crisis and AMLO politics.
| Jan-Sep | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|
| FY (Jan-Dec) | 2019 | 2020 | 2021 | 2022 | 2022 | 2023 | At end Sept | 2023 | ||
| Revenues | 1,844 | 1,111 | 2,200 | 2,847 | 2,027 | 2,302 | Fleet and other fixed assets | 3,815 | ||
| Net result | 140 | (215) | 106 | (80) | (104) | (58) | Current Assets | 430 | ||
| Operating Cashflow | 500 | 198 | 785 | 614 | 446 | 513 | Cash and equivalents | 764 | ||
| Capex and Investments | (99) | (3) | (135) | (131) | (27) | (350) | Total Assets | 5,009 | ||
| Free Cashflow | 401 | 195 | 651 | 483 | 419 | 163 | LT debt and leases | 3,207 | ||
| Financing (inc Lease payments) | (275) | (287) | (435) | (513) | (411) | (132) | Current liabilities | 1,671 | ||
| Equity raised | 149 | Total Liabilities | 4,878 | |||||||
| Total Change in Cash | 126 | 57 | 216 | (30) | 8 | 31 | Shareholders' Equity | 131 | ||
GTF crisis and opportunity
Firstly, there is the industry-wide problem caused by faults in GTF engines manufactured by Pratt & Whitney, requiring accelerated replacement of PW1100G rotors and hubs. This impacts the global A320neo-family of which Volaris operates 72 units with another 145 aircraft due for delivery over the next three to four years.
| In Service | On Order | |
|---|---|---|
| A320ceo | 43 | |
| A321ceo | 10 | |
| A320neo | 51 | 26 |
| A321neo | 21 | 119 |
| Total | 125 | 145 |
The AD issued by the FAA means that aircraft will be taken out of operation for inspections and part replacement, totalling 250-300 work hours per unit, on a rolling basis depending on age and cycles. As at November Volaris had 16 aircraft grounded, which means that that the airline’s annual capacity growth will be zero in the fourth quarter, and overall annual growth for 2023 will be around 10% against a targeted 13%. For 2024, there is likely to be no seat capacity increase.
P&W has allocated $6-8bn to resolve the problem which is comparable to the financial cost of the 737 MAX crisis. Of this total, 20% is for parts and labour ($160,000 per engine) and 80% for compensating airlines for lost revenue.
In December Volaris announced that a “compensation and support package” had been signed with P&W, the details of which are for the moment confidential, but which should cover the fixed costs of the grounded aircraft.
Volaris has outlined a strategy to cope with the impact of the A320neo groundings, which it expects to continue through to 2026. In 2020/21 Volaris set out to turn the Covid crisis into an opportunity, and it seems to be doing something similar with the GTF crisis, with the overall aim of pushing up unit revenues. The strategy includes four main items:
-
Rationalising the domestic route network, cutting capacity on weaker routes and building frequencies on the stronger routes, a plan that, however, has been complicated by political interference at the Mexico City airports (see below).
-
Focusing on ancillaries, the aim being to increase the proportion of ancillaries from 42% to 50%. As well as the usual splitting out of baggage fees, branded credit card, etc there is one innovation: VPass, a membership club that charges a monthly fee in return for guarantees of access to the lowest fares.
-
Extending leases on A320ceo aircraft rather than returning them to the lessors at the end of the lease term; but the unexpected demand for A320-family CEOs, as a by-product of the NEO groundings, has allowed the lessors to increase rates for these types.
-
Importantly, Volaris has been able to redeploy capacity to Mexico-US routes following the restoration in October by the FAA of Category 1 status, permitting Mexican airlines to again add new flights and routes to the US, and for US airlines to sell tickets on Mexican-operated flights, which will allow Volaris to fully reinstate its codesharing alliance with Frontier, another ULCC whose performance has not met expectations in recent months.
As the graph indicates, US carriers controlled two thirds of transborder capacity in 2022, a gap which Volaris and the two other Mexican airlines are determined to close. Also, Volaris claims that it will be able to expand into the US without excessive competition from the US Majors because they concentrate on different markets — Volaris focusing on Mexican-heritage VFR markets and the US airlines on mass tourism markets.
It is likely that the GTF crisis will remove or at least greatly reduce the threat of overcapacity in the Mexican markets in the next two years. All three Mexican airlines have been pumping capacity into the market post-pandemic: in the first nine months of 2023 Volaris increased its total ASMs by 14.4% compared to 2022, Viva Aerobus by 19.4% and Aeroméxico by 11.7%. Both the ULCCs are heavily exposed to the GTF grounding — Volaris currently operates 72 NEOs out of a total fleet of 125 and Viva Aerobus 46 NEOs out of 78 and both have large NEO backlogs, 145 and 115 units respectively. Aeroméxico is a Boeing operator, but it does not have any significant new capacity on order.
From Volaris’s short-term perspective the supply constraint plus the P&W funds might just be a welcome development. In the first three quarters of 2023 it was financially outperformed by Viva Aerobus which increased revenues by 35% to $1.37bn and reported an operating profit of $157m, representing a margin of 11.5% (compared to Volaris’ 2.5% margin at this level).
Aeroméxico’s financials are less transparent, but it too has reported results that appear better than Volaris’s: for the nine months, revenue was $3.54bn, 35% up on the same period in 2022, and a net profit of $179m was claimed against a net loss of $(235m) in 2022.
AMLO and the new airport
While Volaris’s problems with P&W are being constructively addressed, the same cannot be said of its (and most of the Mexican commercial airline industry’s) relations with the country’s President, Andrés Manuel López Obrador (universally known by his initials AMLO). In power since 2018 AMLO, has pursued an anti-corruption agenda, which is highly admirable given the pervasive narco-economy, but has also promoted populist and increasingly eccentric economic policies.
In 2019 AMLO cancelled the new six-runway Mexico City airport initiated by his predecessor to replace the centrally-located but very congested Benito Juárez International Airport (MEX). The cancelled project, designed by Norman Foster Associates, was one third constructed and was expected to cost $13bn. Instead, a former military airport, called Felipe Ángeles (NLU), was converted to commercial use and opened in 2022 with the military in charge of its operations.
Unfortunately for AMLO, airlines were less than keen to relocate to Felipe Ángeles, which is located over 40km from the city centre with poor transport connections — this summer passenger throughput was about 250,000 passengers/month, 12% of the volume at Benito Juárez.
AMLO decided the solution was to be old-style command economics. Freight operations at MEX were halted by presidential decree, and airport charges at MEX were increased and decreased at NLU (these are pass-through charges added to ticket prices so do not directly impact airlines’ revenues or costs).
Most critically, severe slot restrictions were imposed by the government on passenger flights at MEX: in late 2022 the number of hourly slots was cut from 61 to 52, and in January 2024 there will be a further restriction bringing the maximum hourly slots down to 43. In effect, the capacity of MEX has been arbitrarily cut by 30% in one year. Although it has eight operating bases, MEX is Volaris’s main hub where it accounted for about 22% of total ATMs in 2022. Aeroméxico accounts for just over half of MEX’s slots and Viva Aerobus 17%.
All three airlines plus industry bodies, travel agencies and pilots unions have protested loudly. Peter Cerda, IATA’s regional vice-president summarised the airlines’ position: “Making the unilateral decision of just pushing capacity somewhere else... without good analysis, particularly without collaboration, [means] … less availability of flights, fewer destinations and higher prices.” At one point the airport situation threatened the restoration of Mexico’s Category 1 rating, with US officials strongly objecting to the limits placed on cargo and passenger flights at MEX.
AMLO has shown some degree of flexibility by postponing the reduction to 43 hourly slots from October to January in the low season, but he seems determined to press ahead with the forced shift from MEX to NLU, so this policy will continue at least until November 2024 when the next elections are due.
Meanwhile, AMLO’s next move was to set up a new national airline, or rather resurrect a defunct flag-carrier — Mexicana — which stopped operating in 2010 and has been in bankruptcy protection since then. The government spent $43m on buying the Mexicana brand, the money going to several trades unions that were creditors of the bankrupt carrier.
So far, the set-up of the new carrier, administered by the military, has been a mess. The Defence Ministry has reportedly budgeted $300m for the venture and aimed for a September launch but as of the beginning of December it had not obtained an AOC, largely because it had no aircraft. The original plan was to lease 10 737-800s from a US company called SAT Aero Holdings, which would also provide maintenance services and source flying crew, but this arrangement appears to have collapsed, leaving Mexicana searching for 737NG equipment.
AMLO’s stated aim for Mexicana is to offer fares 20% below the local competition. Given that Volaris has one of the lowest unit operating costs in the Americas — CASM of US¢4.3 ex-fuel in 2022, very close to that of Wizz — the Mexicana strategy seems highly implausible.
Volaris management is dismissive of any competitive threat from Mexicana but the militarisation of Mexico’s aviation infrastructure is worrying. The army and navy now control 23 airports, including the two Mexico City airports and the just opened Tulum Airport on the Yucatán peninsula.
Fundamentals
Looking beyond the external problems, Volaris’s fundamentals still look very promising (as do those of Viva Aerobus which shares many of Volaris’s characteristics).
-
Volaris remains Latin America’s biggest ULCC with about 34m passengers in 2023. It has embraced all the key elements of a Ryanair-type ULCC model — yield-driven demand, flexible asset location, high productivity, rigorous cost control, clear decision-making processes, concentration on VFR and Leisure segments, 50% revenue from ancillaries, etc. More importantly, there is a stable, long-established management team under CEO Enrique Beltranena, and it has Indigo Partners, led by Bill Franke, as its strategic partner.
-
Volaris’s CASM (ex-fuel and adjusted to a 1,000km trip) of US¢4.3 compares to US¢6.9 for the US ULCC Frontier, US¢9.7 for the US LCCs as a group and US¢14.0 for US Legacies — so an operating cost advantage of 40-60% against the main rivals; however, Viva Aerobus’s CASM is approximately the same.
-
In spite of the current hiatus, Mexico’s air travel market has the potential to grow rapidly. Domestic trips per capita doubled between 2006 and 2019, and if Mexico were to achieve the same ratio as Chile, an additional 47m passengers would be generated. 51% of Volaris’s routes compete solely against buses, and if Volaris were to convert 10% of the luxury bus segment it would double its domestic passenger volume.
-
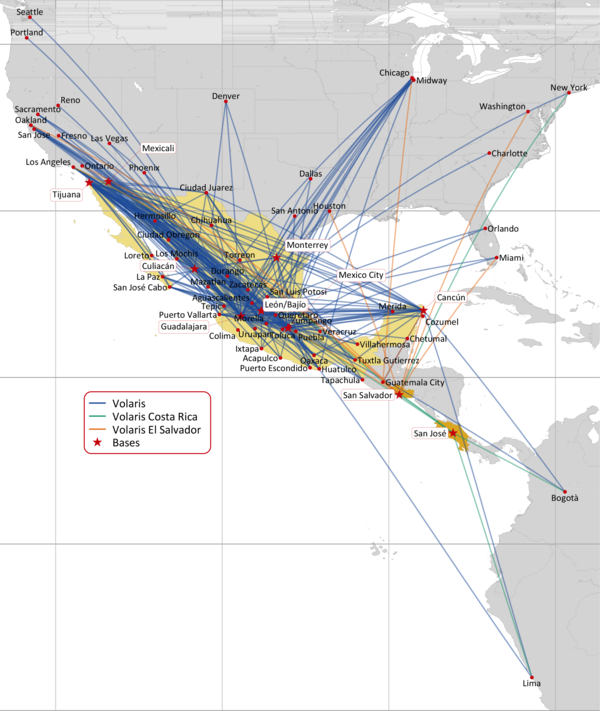
International expansion is mainly focused on the US following the restoration of Category 1 and the codesharing alliance with Frontier, but Central and South American markets, where ULCC penetration is very low, are also promising. Volaris expects these markets to account for 14% of its network in the medium term against 6% currently.
-
Despite the GTF crisis growth plans remain centred on the A321neo: by 2027 contracted deliveries will build the planned fleet up to 162 units, 98% of which will be 239-seat A321s. Volaris has a built-in cost advantage due to the unit pricing achieved by Indigo Partners when it placed its mega-orders for 430 units in 2017 and 382 units in 2021, of which 80 and 64 respectively are allocated to Volaris.